China’s latest efforts to prop up its stock market are unlikely to reverse the decline without a broader economic recovery, analysts say, warning that weak corporate earnings, sluggish consumer demand, and low business investment continue to undermine investor confidence.
The Chinese regime announced a series of market support measures on Nov. 2 as the country’s stocks continued to slide. The measures reflect Beijing’s concern that a prolonged sell-off could trigger panic among investors, threaten financial stability, and undermine funding for strategic industries such as AI, analysts told The Epoch Times.
However, they cautioned that injecting liquidity and encouraging share buybacks cannot resolve the underlying economic problems.
China’s three major financial regulators announced that a lending program supporting share repurchases and increased shareholdings would become a permanent policy rather than a temporary arrangement. The regime also lowered the program’s interest rate from 1.25 percent to 1 percent.
China’s central bank also began conducting overnight reverse repurchase operations every business day, at an interest rate of 1.25 percent, to manage short-term liquidity, according to state news agency Xinhua.
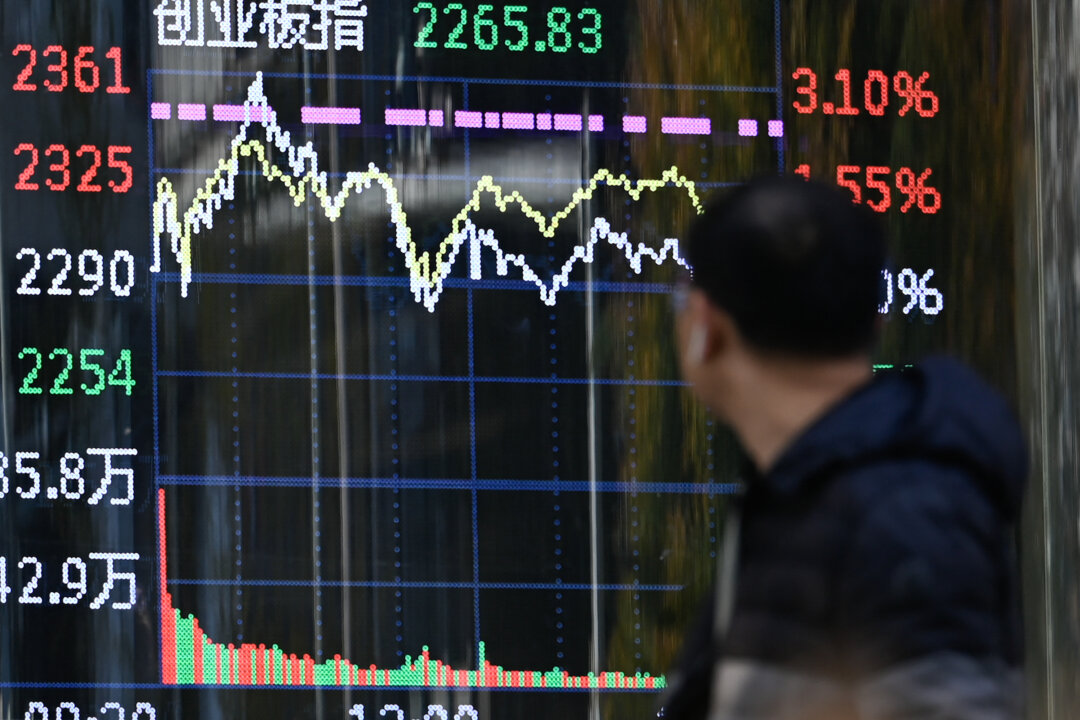
China’s tech-heavy STAR 50 Index fell about 40 percent in less than four months, wiping out approximately $480 billion in market value. The CSI 300 Index also entered bear-market territory last month, falling more than 20 percent from its recent peak.
Xu Zhen, a senior professional in China’s finance sector, told The Epoch Times that the latest decline reflects not only weak economic fundamentals but also concerns about state intervention and deteriorating market confidence.
He said investors should not mistake the latest measures for a genuine commitment to supporting ordinary shareholders.
“The Chinese Communist Party (CCP) does not do charity for stock investors,” Xu said. He described the overnight reverse repurchase operations as little more than a market placebo.
Xu said Beijing’s primary concern is not the losses suffered by individual investors but the possibility that a continued decline could trigger panic selling and threaten financial stability.
He also argued that the regime had hoped to channel household savings into the stock market to help finance China’s AI ambitions. A prolonged market downturn could make that strategy more difficult and weaken China’s position in its tech competition with the United States.
Davy Jun Huang, a U.S.-based political economist and former columnist for Chinese state media outlet CNTV, told The Epoch Times that Beijing’s intervention reflects concerns that a weak economy and falling stock prices could reinforce each other.
A sustained decline could further erode household wealth, reduce companies’ access to financing, and increase risks for financial institutions holding stocks as collateral, he said. That could create a vicious cycle in which struggling businesses reduce investment and hiring while households cut spending.

Struggling to Restore Investor Confidence
Huang said the central bank’s overnight reverse repurchase operations are designed to provide short-term funding to financial institutions, reducing the risk that temporary cash shortages force them to sell assets or restrict lending.
However, he cautioned that the policy should not be mistaken for a broader interest rate cut. The daily operations do not necessarily mean the central bank is injecting the same amount of new money each day.
Xu argued that liquidity was not the main problem behind the stock market decline.
“Overnight reverse repurchase operations send a technical signal, not a market-rescue signal. They cannot save the stock market from falling,” he said.
He noted that October data show that the average overnight interbank repurchase rate was about 1.28 percent, while the ChiNext and STAR 50 indexes fell 23.02 percent and 24.13 percent, respectively.
“The decline is driven by selling pressure from state-backed funds, the AI bubble, and a loss of confidence in the government, not a shortage of money,” Xu said. “Businesses have no orders, so even cheaper money won’t encourage them to borrow.”
Huang similarly said companies’ borrowing decisions depend more on future orders, capacity utilization, and market demand than on interest rates alone. Businesses facing excess production capacity and insufficient orders are unlikely to expand investment simply because loans become cheaper.
Households face similar concerns, he said.
“Families worry about income, employment, retirement, healthcare, and education. Even if they have sufficient funds, they will not increase consumption,” Huang said.
Both analysts said the share repurchase lending program might provide short-term support for stock prices but would not create a sustainable bull market.
Huang noted that buybacks can benefit shareholders when financially sound companies with strong cash flows repurchase undervalued shares and cancel them, reducing the number of shares outstanding.
However, companies with weak business performance that repeatedly borrow to buy back their own shares could increase their debt burdens without improving underlying profitability.
Economic Weakness
China’s latest economic indicators underscore the challenges facing policymakers.
The regime’s National Bureau of Statistics reported that the manufacturing Purchasing Managers’ Index (PMI) fell to 49.3 in October, while the non-manufacturing business activity index declined to 49.7. Both were below the 50-point threshold separating expansion from contraction.
Huang said stock market performance does not necessarily reflect the condition of the broader economy because share prices are also influenced by investor expectations, state policies, and interest rates.
He cited China’s property sector as an example. Official figures showed that real estate development investment fell 20.6 percent year over year in the first nine months of 2026, even as some property-related stocks showed signs of improvement.
A recovery in those stocks does not mean home sales have recovered or that property developers have reversed their financial difficulties, he said.
Huang said a sustained stock market recovery ultimately depends on improvements in corporate operations and profitability, as well as stronger household incomes and investment confidence.
“A stock market that relies on government policies to maintain asset prices over the long term means that both business development and the market are unhealthy,” he said.
Li Haoyue and Luo Ya contributed to this report.
We had a problem loading this article. Please enable javascript or use a different browser. If the issue persists, please visit our help center.